How LOOP Biz gives merchants access to business tools without changing the bank they already trust
A small business can spend years building its banking relationships. The account used to receive customer payments may also be linked to supplier arrangements, standing orders, payroll and other routine obligations. Changing banks can therefore involve more than opening a new account. It can mean reviewing processes that have become part of how the business operates.
That can make business owners cautious when considering new financial technology. A payment platform or business-management service may offer useful capabilities, but merchants may hesitate if using it appears to require moving their existing banking arrangements.
This is one of the considerations behind LOOP Biz’s bank-agnostic positioning. NCBA’s merchant platform is designed to let businesses use its payment and business tools without requiring them to move their entire banking relationship to NCBA.
For merchants, the distinction is practical. They can consider the platform’s services based on their operational needs while retaining banking arrangements that already work for their businesses, subject to the requirements of individual services.
Separating business tools from the banking relationship
Small businesses use financial services in different ways. A retailer may receive payments through a bank account, use a separate mobile money Till and rely on another provider for a particular business service. These arrangements often reflect the needs of the business at different stages of its development.
A merchant considering a new payment device may therefore want to know whether it can fit into the existing setup. The same question applies to digital inventory tools, transaction reporting and potential access to business credit.
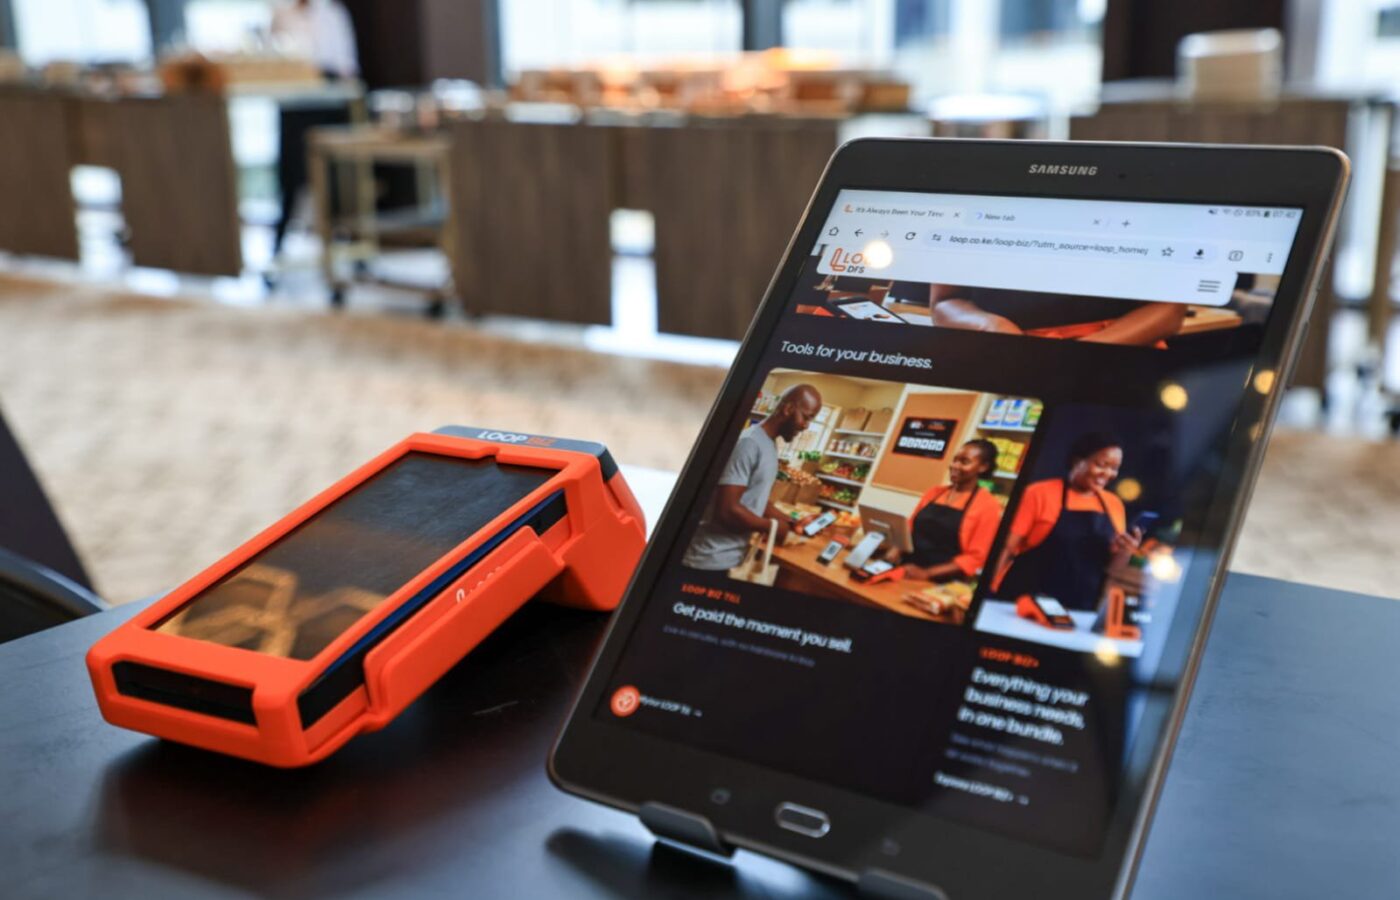
LOOP Biz brings several of these services into one merchant platform. Its PDQ device supports Visa and Mastercard chip and contactless payments, M-Pesa Till and Paybill, M-Pesa STK push and LOOP STK push. Inventory management is available as a paid addition for eligible businesses using the web platform.
The platform’s bank-agnostic approach means merchants do not have to transfer all their banking activity to NCBA simply to use LOOP Biz. This can lower one potential barrier to considering the service, although it does not remove the need to meet the conditions attached to specific products.
What merchants should understand about credit
The distinction between using a business platform and qualifying for credit is particularly important.
LOOP Biz uses merchant transaction activity as part of its approach to assessing businesses for credit. The campaign information states that merchants do not have to move their primary banking relationship to NCBA to use the platform or be considered for credit.
However, consideration for financing remains subject to the bank’s requirements. The campaign brief identifies a registered business, completed KYC requirements and an active LOOP Till among the eligibility conditions. Credit is also subject to assessment and approval.
A merchant should therefore avoid assuming that using the platform automatically qualifies the business for a loan or overdraft. The availability, amount, cost and repayment terms of any facility need to be assessed separately.
For a business owner, this means being able to evaluate the payment and management tools on their own merits while understanding that lending remains a separate decision.
Choosing services around the needs of the business
Bank-agnostic access also raises a broader question about how businesses evaluate digital services.
A retailer may be interested primarily in accepting card payments. Another may need a better way to monitor stock, while a growing business with several employees may place more importance on reporting and staff permissions.
The right decision depends on the problem the business is trying to address. Merchants should consider the supported payment methods, subscription costs, device requirements, compatibility with existing processes and the level of access available to employees.
They should also establish whether a feature is included in the core service or carries an additional charge. LOOP Biz’s PDQ and inventory management, for example, have separate pricing arrangements in the campaign information. The inventory subscription is listed at KSh1,990 per month before tax, while the PDQ has its own subscription or one-off payment arrangement.
Understanding those costs helps a merchant assess the platform as part of the business’s operating expenses rather than treating every feature as part of one bundled service.
Keeping flexibility in the digital transition
Digital business services are becoming part of everyday retail operations, from accepting customer payments to keeping stock records and reviewing sales activity. For smaller businesses, adopting these tools needs to fit around existing systems and financial commitments.
LOOP Biz’s bank-agnostic positioning gives merchants the option to consider its services without first transferring their wider banking relationship. That flexibility may be relevant to businesses that want to improve a particular part of their operations while retaining arrangements they already rely on.
The decision still requires a careful review of product terms, costs and eligibility. But merchants can begin by asking a straightforward question: does the service solve an operational problem, and can it work within the way the business already manages its money?
Follow us on X, Instagram and Facebook for the latest stories, trends and updates from Nairobi and beyond.