How KCB Made Kshs. 68.4 Billion in a Tough Year for Banks
KCB FY2025 Results Show Profit Growth as Lending and Regional Units Drive Earnings
The KCB FY2025 results show how the bank grew its earnings in a year shaped by high interest rates and tighter credit conditions. KCB Group Plc reported KShs. 68.4 billion in profit after tax, an 11 percent increase from 2024. The numbers reflect steady loan growth, rising interest income and a wider regional presence.
Revenue climbed to KShs. 214 billion, up from KShs. 204 billion the previous year. The increase came largely from lending to households, businesses and the public sector. For you as a reader or investor, that points to one clear trend. Credit remains the main driver of bank earnings in Kenya.
Lending Continues to Drive Income
KCB expanded its loan book to KShs. 1.59 trillion, a 15 percent increase. That growth pushed interest income higher and lifted total earnings. Interest-earning assets also rose to KShs. 1.84 trillion, showing how much of the bank’s balance sheet now sits in income-generating instruments.
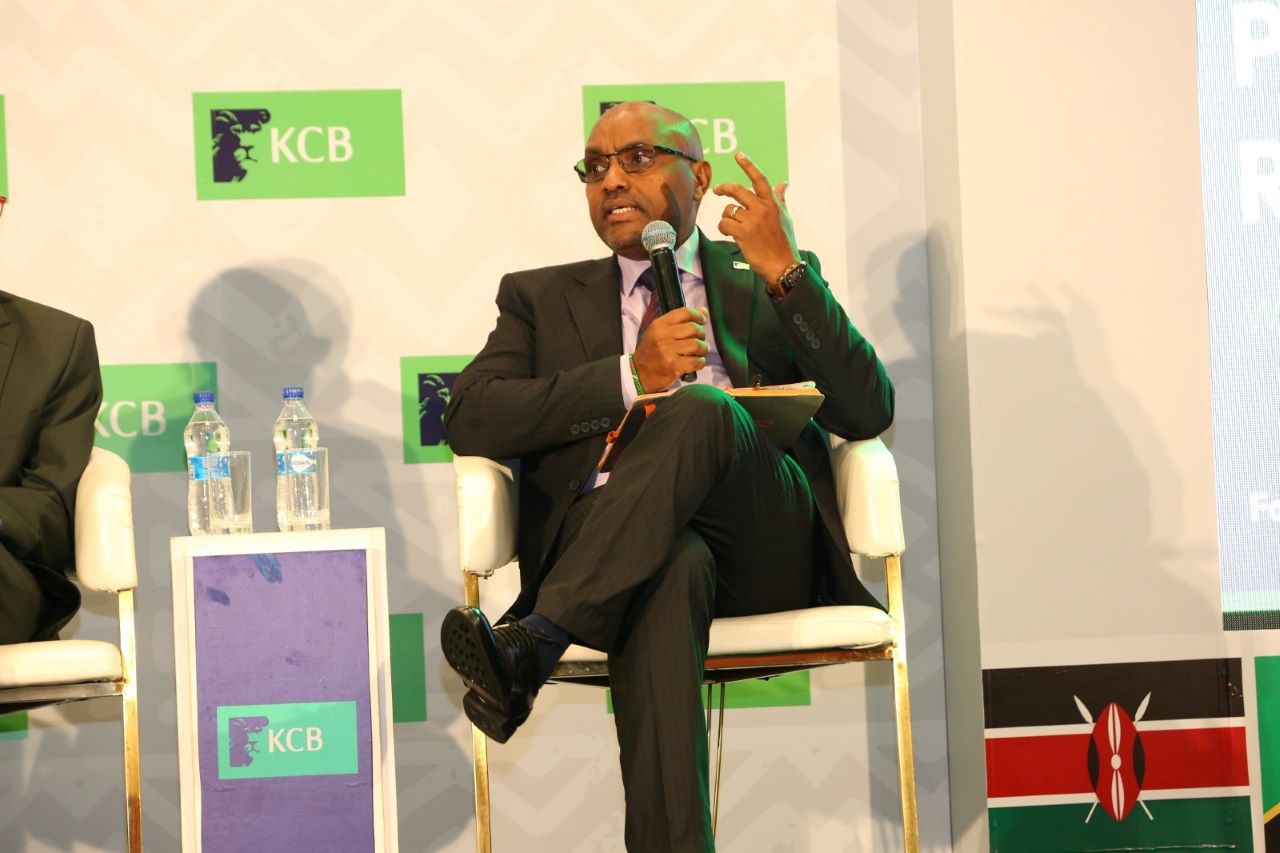
Chief Executive Officer Paul Russo said the results reflect consistent execution and customer demand across sectors.
“Our 2025 performance reflects the strength of the KCB franchise, the resilience of our regional footprint, and the continued trust that customers place in us. Despite a challenging operating environment, we delivered solid growth driven by disciplined execution, continued investment in digital innovation, and our unwavering commitment to supporting sector-focused lending that catalyzes economic transformation across the region.”
Non-funded income contributed 31 percent of total revenue, supported by digital banking services. This shows the bank continues to build income streams beyond traditional lending.
Regional Business Gains Ground
KCB’s operations outside Kenya contributed over 30 percent of profit before tax. This share has been rising in recent years as the bank grows in markets such as Uganda, Rwanda and the Democratic Republic of Congo.
Total assets reached KShs. 2.15 trillion, even after the bank exited National Bank of Kenya. Deposits grew to KShs. 1.59 trillion, giving the bank enough liquidity to support further lending.
Costs Drop but Loan Risks Remain
The bank reduced its cost-to-income ratio to 42.5 percent, down from 45.4 percent. Operating expenses fell slightly, which helped protect profit margins.
Loan quality improved, with the non-performing loan ratio dropping to 16.9 percent from 19.2 percent. The figure remains high by industry standards, and it shows that some borrowers still face pressure.
KCB cut its stock of bad loans to KShs. 211.8 billion, supported by recoveries and restructuring.
Shareholders Get Higher Payout
Investors will receive a total dividend of KShs. 7 per share, including a final payout of KShs. 3. That brings the total distribution to KShs. 22 billion.
Board Chairman Joseph Kinyua said the bank expects steady economic activity across its markets, though global risks remain.
“Looking ahead, we are optimistic about sustained business activity and economic growth prospects this year across the markets we operate in. We are closely watching the increased global uncertainties attributed to heightened geopolitical tensions and higher tariffs.”
For you, the KCB FY2025 results show a bank that continues to rely on lending and regional expansion to grow earnings, while keeping costs in check and managing loan risk in a tight economic environment.