Liberty Kenya Secures AA+ Rating
Liberty Life Kenya and Heritage Insurance Secure AA+ Credit Ratings from GCR
Liberty Life Kenya and Heritage Insurance Kenya, both subsidiaries of Liberty Kenya Holdings, have attained an AA+(KE) Financial Strength Rating with a Stable Outlook from Global Credit Rating (GCR), an affiliate of Moody’s.
The ratings reaffirm the group’s position among Kenya’s strongest and most financially resilient insurers, reflecting a robust financial profile anchored by strong capitalisation and a conservative investment strategy. The assessment is further supported by strategic integration and backing from Standard Bank Group.
The synchronized AA+ ratings signal a high level of confidence in the group’s financial strength and its ability to meet long-term obligations to policyholders, even amid challenging economic conditions. GCR highlights the businesses’ strong balance sheet, high liquidity, and disciplined investment approach as key strengths underpinning the ratings.
Credit ratings remain a critical indicator of an insurer’s financial health, particularly for customers with long-term products such as life cover, pensions, and investment-linked solutions. An AA+ rating places Liberty Kenya among the top-tier insurers in the Kenyan market, offering added assurance on the security of insurance benefits, savings, and long-term financial commitments.
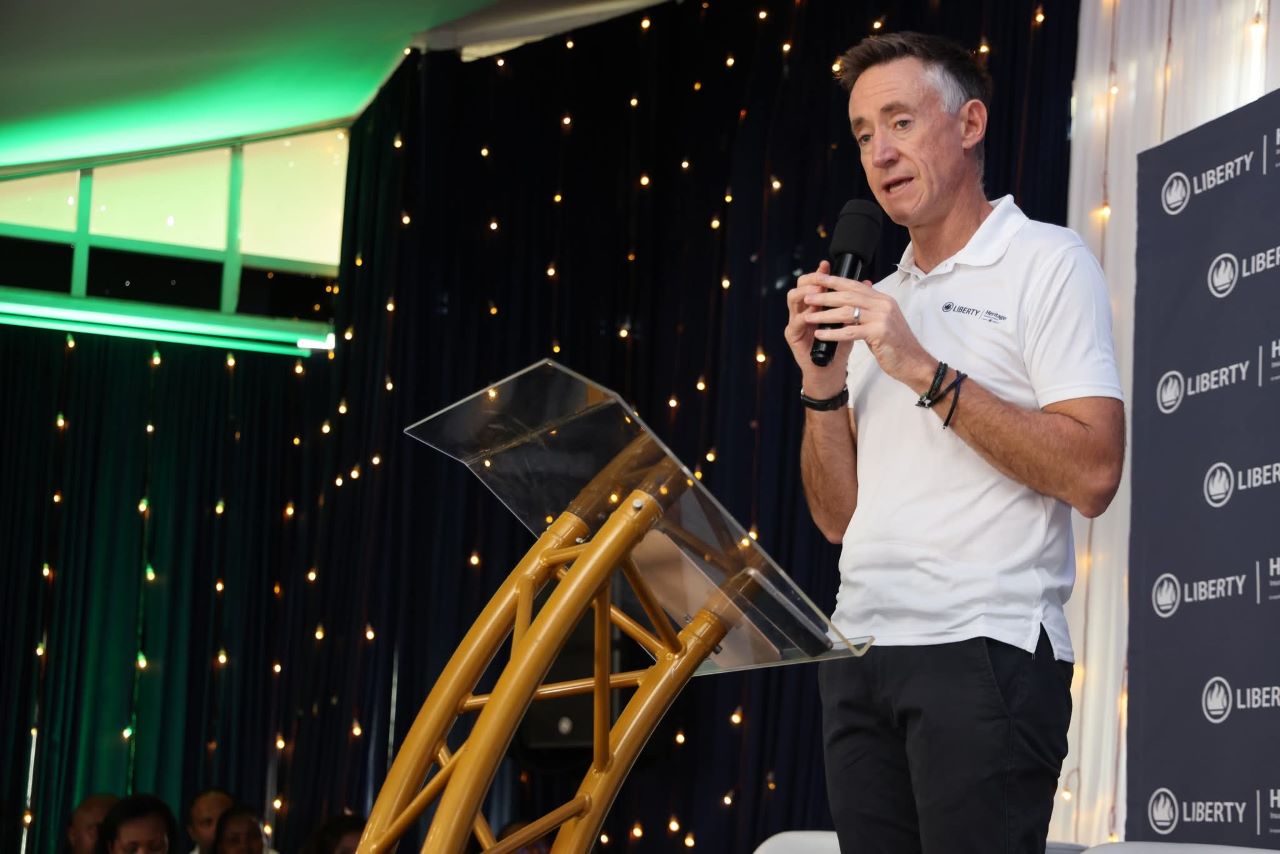
Commenting on the achievement, Liberty Kenya Holdings Chief Executive Officer Kieran Godden said:
“This rating reflects our unwavering commitment to financial discipline and policyholder security. For our customers, it provides independent confirmation of our financial strength and our ability to support them when it matters most. It also affirms our focus on prudent risk management, strong governance, and long-term sustainability.”
The unified AA+ ratings across both operating subsidiaries highlight a diversified and resilient business model that balances underwriting performance with sound investment income. According to GCR, Liberty Kenya’s financial position is underpinned by a strong capital base and a highly liquid asset portfolio, with the majority of investments held in cash, deposits, and government securities. Improved group-level earnings, supported by disciplined investment management and robust risk controls, further reinforce the positive outlook. GCR expects capitalisation and liquidity levels to remain strong, providing a stable foundation for continued service to policyholders.